You found this on your own
Start here.
This is what we do, what it costs, and what happens if you call. It does not matter whether you have an attorney yet, or whether you plan to hire one at all. Nothing on this page asks you to decide anything today.
Start where you are
Most of what you read about divorce assumes you are at the beginning. You may not be. What matters this week depends on where you are, so start there.
Tap the one closest to where you are
Pick one above and you will see what matters now, what can wait, and whether a call is worth it at that point.
A note from me
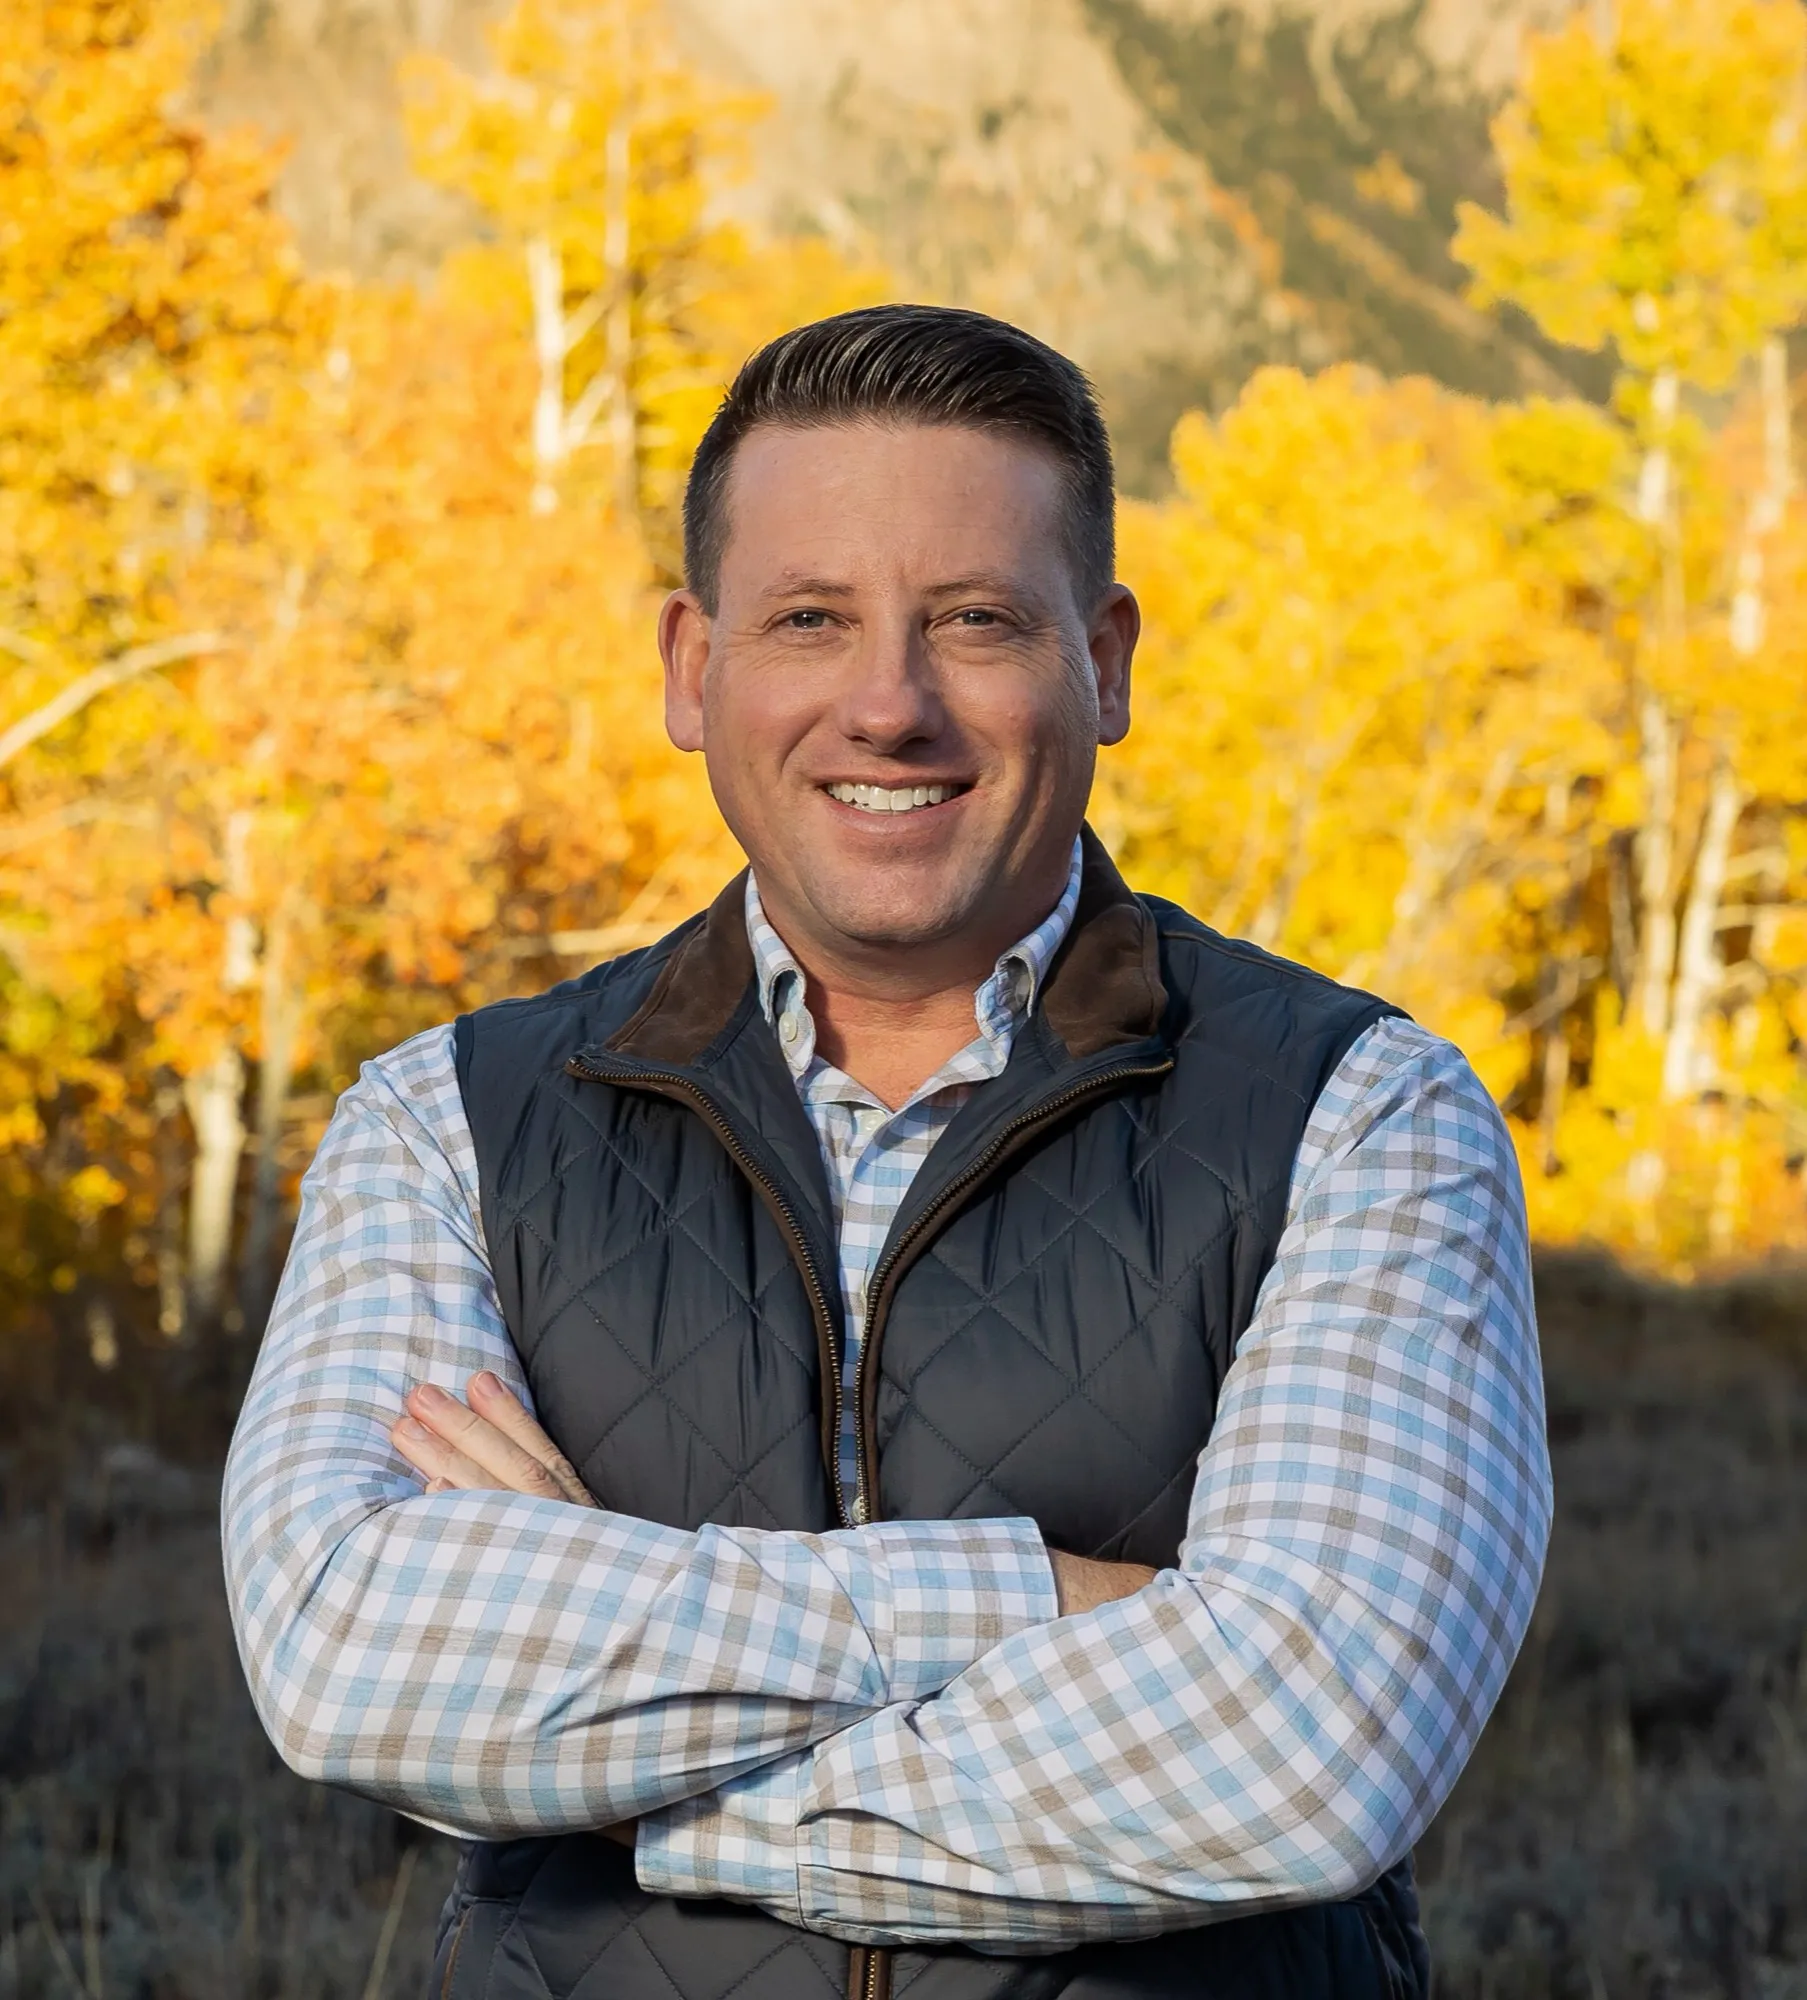
I am Bob Mitton, a Certified Divorce Financial Analyst. I do one narrow thing: I make the money side of a divorce make sense to the person living through it.
I am not your attorney, and I am not trying to manage your investments. I am the person who can tell you what a settlement offer actually does to your life in year ten, while there is still time to do something about it.
I have been through a divorce myself. Most of this guide is what I wish someone had handed me.
If that is the part you are missing, the only way to find out is a conversation, and that part is free.
Equal isn’t fair
Two piles of assets can look equal on paper and behave completely differently once taxes, timing and the cost of carrying them are counted. Almost every settlement that fails, fails on that, not on the total.
Ask four questions of anything on the table:
- How is it taxed?Money in a traditional 401(k) or IRA hasn’t been taxed yet. Money in checking has.
- What does it cost to reach?Selling a house costs commission and closing costs. Some retirement money carries a penalty if taken early.
- When can you use it?Cash is available now. Home equity arrives when the house sells. A pension may pay decades from now.
- What does it cost to hold?A house has to be carried every month: mortgage, taxes, insurance and repairs.
Three assets, each worth $300,000
Move the slidersIllustration only, before state income tax, before any early-withdrawal penalty, and ignoring the cost of carrying the house until it sells. Your own numbers depend on your situation. General education, not tax advice.
Mistakes people live with longest
None of these come from anyone being careless. They come from rules that are specific, paperwork that is unforgiving, and decisions made while tired.
Treating a 401(k) dollar like a checking dollar
- What it looks like
- A $300,000 retirement account and $300,000 of home equity sit on the same line, so the split looks even.
- What to ask
- What is each asset worth to me after tax, and after what it costs to reach?
Assuming the decree moves the money
- What it looks like
- The divorce is final, and a year later the 401(k) or pension still has not been divided.
- What to ask
- Who is drafting the order for each plan, and when will the plan accept it?
Rolling the money before you need it
- What it looks like
- Retirement money awarded under a court order is rolled into an IRA right away, and then cash is needed.
- What to ask
- Will I need any of this money in the next few years? There is a narrow window to take cash from the plan without the early-withdrawal penalty, and rolling first closes it.
Overlooking the survivor benefit
- What it looks like
- You were awarded part of a pension, and it stops when your former spouse dies.
- What to ask
- Does my share continue if my former spouse dies first? That protection is negotiated and written in. It is not automatic.
Keeping a house one income cannot carry
- What it looks like
- The house stays, for the kids, and two years later the taxes, insurance and repairs force a sale anyway.
- What to ask
- Can one income carry the mortgage, taxes, insurance and upkeep? And whose name stays on the loan?
Signing in the tired middle
- What it looks like
- Months in, the only goal left is for it to be over, and a term that would have been questioned in month one gets accepted.
- What to ask
- Am I agreeing to this because it works, or because I am worn down? Being reasonable and being exhausted are different things.
What a month of your life costs
In many marriages one person handles the money and the other handles everything else. It works, until the divorce asks you to decide about accounts you have never looked at. You don’t need to become a financial expert. You need to see what is there, what it costs to live, and what each choice means over time.
Almost everything rests on one number: what a month costs once you are on your own. Rebuild it from a year of bank and card statements rather than from memory, then adjust it for life after.
Your monthly number
Type rough amountsNothing you type here is saved or sent anywhere unless you choose to bring it to our call. Close the page and it clears.
That number drives support conversations, and it tells you which settlement options you can actually live on. If you have been out of work for years, the other half of the picture is what you could earn: what your old work pays now, whether a course or license would raise it, and how many hours you can realistically work around the kids.
What to gather
This is the full list. You will not have all of it, and some of it will not apply to you. That is normal. Start with the first six; they carry the most weight. If you don’t know where something is, write that down too. A gap only becomes a problem when nobody knows it is there.
You don’t need any of this for a first conversation. If we do work together, you will upload documents through a secure portal, never by email.
Start with these six
Tap what you have: 0 of 55Income and work7
Bank and investment accounts6
Retirement6
Stock and deferred pay3
Real estate4
Debts5
Insurance4
A business4
The children3
What was yours before3
Legal and other4
A PDF is easiest, but a clear photo of a paper statement is far better than nothing. Name each file so it can be told apart at a glance: institution, last four of the account, statement date.
WellsFargo_1234_2026-03-31.pdfNothing you tick here is saved or sent anywhere unless you choose to bring it to our call. Close the page and it clears.
Doing it together
Not every divorce is a fight. Plenty of couples want to divide things fairly, protect the kids, and move on with as little damage as possible. For them, I can work as a neutral: one analyst, working for both of you, building one set of numbers you both trust.
- One shared listEverything you own and owe, built together, so neither of you is negotiating from a different spreadsheet.
- Options, not a sideEach option modeled for both households, so you can see what it does to each of you in year one and year ten.
- Agreed at the startWhether I work for one of you or both of you is settled before any work begins, and it does not change partway through.
- Alongside your attorneys or mediatorNeutral work fits mediation and collaborative divorce, and it works whether or not either of you has hired counsel.
If one of you has already talked with me, I will tell the other before we go further. That is part of what makes neutral work trustworthy.
Read Even Isn’t Always Fair, a short guide written for couples doing this together.
Your state, not a template
Divorce law is state law. What counts as marital property, which date closes the marriage’s finances, and how support is decided all change from one state to the next. Two couples with the same balance sheet can come out very differently in two states.
I work with people across the country, and every case is worked from that state’s current rules. The library behind it covers all 50 states and the District of Columbia.
A short summary for illustration, not legal advice. Your attorney’s read of the law governs.
What happens if you call
- 1
A conversation, about twenty minutes
You tell us what is happening. No documents to gather first, no cost, and nothing you have to decide at the end of it.
- 2
We tell you honestly whether we can help
Sometimes the answer is that your situation does not need us, and we would rather say so than take the engagement. That happens more often than you might expect.
- 3
If we can help, you get a scope and a number
Before you commit to anything. You will not get a surprise invoice from us.
- 4
Then the work
We build the financial picture, model what each option actually does to your life over time, and give you something you can understand and hold in front of you, whether that is in a mediation, across a table, or on your own before you answer.
What this costs
Every situation is different, so I don’t put a single price on a page and pretend it fits everyone. What I will do is tell you the number before you agree to anything, and tell you plainly if I think the work isn’t worth it for your situation.
The first conversation costs nothing, and it isn’t a sales call. If it turns out you don’t need us, that is a good outcome, and I will say so.
Questions people ask
Do I need this if I already have a good attorney?
They are different jobs. Your attorney handles the law and the negotiation. We handle what the numbers underneath actually do over time: taxes, liquidity, what a settlement looks like in year ten. Good attorneys are usually the ones who ask for this, because it makes their negotiation stronger.
What if I do not have an attorney?
That is common and it is not a problem. Some of the people we work with are handling their divorce themselves. Others have not hired anyone yet, or plan to bring someone in only at the end. The financial work is the same either way, and none of it depends on you having retained counsel first. We are not a substitute for legal advice, and if you reach a point where you need it, we will tell you plainly.
Are you trying to take over my investments?
No. We do not manage money and we are not looking to. If you already work with a financial advisor, our job is to hand you back to them with a clean starting point rather than to replace them.
Can you work with both of us?
Yes, in the right circumstances. We can work as a financial advocate for one person, or as a neutral helping both sides understand what is being decided. Which role applies is agreed at the start and does not change partway through.
When is the best time to bring you in?
Earlier than most people do. The structure of a settlement is movable while it is being negotiated and effectively permanent afterwards, so the value is highest before anything is agreed.
Do you give legal or tax advice?
No. Tidal Pointe Advisors is not a law firm or an accounting firm. If you have an attorney or a CPA, we work alongside them rather than in place of either. If you do not, we still do not fill those roles, and we will say so when something calls for one.
Guides to keep
Short guides, each written for one situation. Read them on your own, or share them with whoever is helping you.
- When You Didn’t See It ComingThe first 30 days, one step at a timeOpen the PDF
- The Money You Never Had to ManageWhen the finances were never your jobOpen the PDF
- Even Isn’t Always FairFor couples dividing it togetherOpen the PDF
- The Half That Fits Your LifeComparing what is actually on the tableOpen the PDF
- Seven Retirement Splits That Cost YouThe retirement mistakes I see mostOpen the PDF
- The First Thing I Wish I’d KnownA note for the middle of itOpen the PDF
- 16 Questions to Ask Before You Hire Your AttorneyFor anyone about to retain counselGet the guide
General education, not legal or tax advice. This page counts which of its tools get used, anonymously, so it can get better; nothing you type or tick is included. Last updated November 2026.
Bring this to our call
OptionalIf you used any of the tools above, you can bring what you entered to our first conversation, so we don’t spend the first ten minutes on it. Here is exactly what would be added to your booking. Change or delete anything.
It goes into the notes on the booking form, where you can still edit it before you confirm. Nothing is sent until you book.
When you are ready
A short conversation, at no cost. You tell me what is happening, and I tell you honestly whether I can help. If now is not the right time, this guide will still be here.
Book a conversationOr call (843) 919-0199.